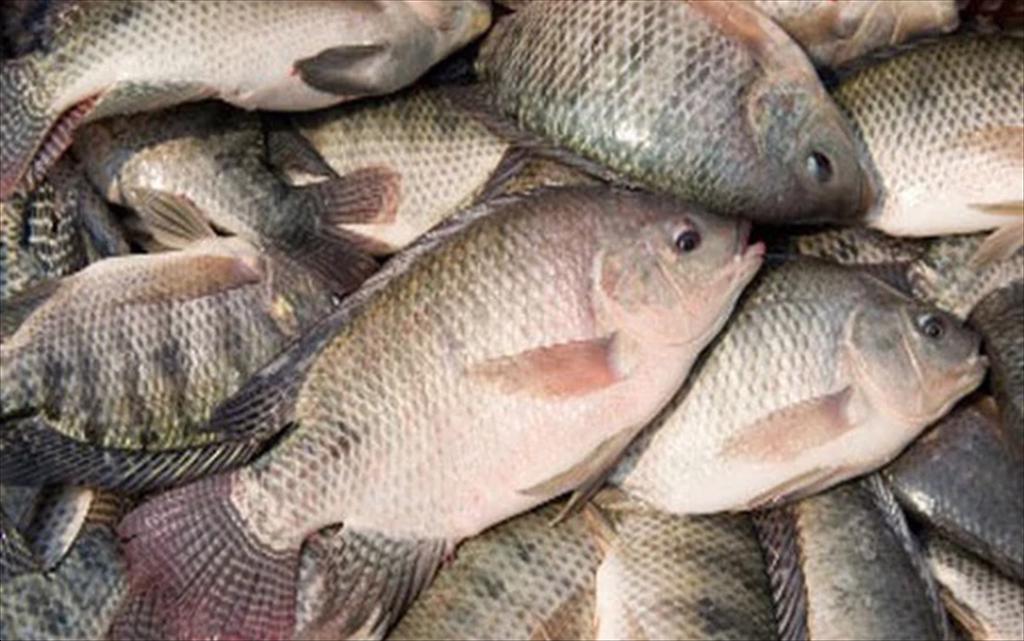
According to the INFOFISH Tilapia 2025 report, China remains the world’s leading tilapia producer. In Asia, Indonesia ranks second, followed by Bangladesh and Vietnam.
Three Supply Groups with Different Product Advantages
The first group comprises China, Vietnam, Indonesia, and Taiwan, which have the capacity to supply large volumes of frozen tilapia. These countries compete directly in the whole-fish and frozen-fillet segments, serving markets that prioritize competitively priced products.
China remains the most prominent supplier in the frozen segment. In the first quarter of 2026, its exports of frozen whole tilapia rose sharply, particularly to Côte d’Ivoire, while shipments to the United States declined significantly. This suggests that China may be redirecting its exports toward other markets, especially Africa, rather than reducing its supply capacity.
Meanwhile, Brazil, Colombia, Mexico, Honduras, and Costa Rica are strong in the fresh-fillet segment. Their geographic proximity to the United States gives them an advantage in meeting requirements for short transit times and product freshness.
The remaining group includes Egypt, Bangladesh, the Philippines, and Thailand. Although these countries have substantial production volumes, a large share is consumed domestically, meaning that not all their output enters international trade in significant quantities. In other words, high production does not necessarily translate into strong competitiveness in global markets.
Trade Flows Are Shifting
The most noticeable changes are taking place in the US market. China remains the largest supplier, but its shipments have declined, while Indonesia and Vietnam are beginning to gain market share in the frozen-fillet segment.
The decline in Chinese tilapia supplies to the United States does not mean that demand for tilapia has disappeared. Rather, the supplier mix and product composition are changing. FAO GLOBEFISH also reported that global tilapia trade continued to shift toward more competitively priced frozen products in 2025.
Brazil presents another notable development. Despite being the world’s fourth-largest tilapia producer, Brazil recorded imports exceeding exports for the first time during the first eight months of 2026, as imports of frozen fillets from Vietnam increased sharply. This demonstrates that even countries with well-developed aquaculture industries may turn to external suppliers when imported products meet their needs in terms of price, specifications, or supply capacity.
Opportunities and Challenges for Vietnam
In the frozen-product segment, China and Indonesia are Vietnam’s two direct competitors. In the US fresh-fillet market, Colombia, Honduras, Costa Rica, and Brazil hold a competitive advantage.
Vietnam benefits from the experience and capabilities developed by its pangasius industry. Its value chain, from farming areas and raw-material procurement to processing and exports, is relatively well established. Processing plants that meet stringent US and EU standards, cost-control capabilities, and favorable natural conditions for expanding farming areas are additional strengths.
These advantages are reflected in the country’s export growth. In the first eight months of 2026, Vietnam’s tilapia exports reached US$90 million, up 43% year on year. Brazil accounted for US$44 million, nearly half of the total export value, while shipments to the United States reached US$21 million.
However, the heavy concentration of exports in Brazil also creates risks. Brazil’s domestic aquaculture industry is responding to the rapid increase in imported fillets, citing concerns about price competition and disease. Market diversification is therefore an urgent priority. Vietnam’s competitiveness will depend not only on pricing but also on its ability to deliver value-added processing, consistent quality, traceability, and products targeting higher-value market segments.
Overall, the global tilapia market is not facing an absolute shortage of supply. The key issue is the segmentation of supply by product type, destination market, and logistical advantages. This ongoing realignment is creating new opportunities for Vietnam, while also intensifying direct competition among producing countries.
(vasep.com.vn) Markets are changing faster, buyer requirements are becoming more demanding, and trade barriers are growing increasingly complex. In this environment, seafood businesses need more than an understanding of current market conditions. They need a longer-term perspective to answer a critical question: Where will growth opportunities come from in 2027–2029, and what should businesses do now to prepare? This is one of the key reasons why VASEP is organizing Vietnam Seafood Summit 2026.
(vasep.com.vn) In the first eight months of 2026, Vietnam’s pangasius exports to the Middle East reached US$113 million, up 7% year on year from the same period in 2025. Growth has become more pronounced in recent months. In August alone, exports to the region totaled US$20 million, an increase of 24%. This indicates that demand for Vietnamese pangasius in the Middle East is gradually recovering after a slowdown in March, although the pace of recovery varies across markets.
(vasep.com.vn) China’s shrimp imports continued to grow strongly in 2026, while Vietnam’s shrimp exports to the market also recorded notable growth. However, behind these positive figures lie two distinct trends: Chinese consumption is growing more slowly than imports, and lobster accounts for a substantial share of Vietnam’s shrimp exports to China, making its product mix significantly different from those of Ecuador and India. Exporters therefore need to assess each segment carefully to understand the opportunities and risks.
(vasep.com.vn) Changing markets, shifting buyer demand, and increasingly complex trade barriers are raising a key question for Vietnam’s seafood industry: Where will the new growth opportunities lie in 2027–2029?
(seafood.vasep.com.vn) As of the end of August 2026, Vietnam’s tilapia exports to the United States reached $21 million, representing a steep 48% year-over-year decline and accounting for 23% of the country's total tilapia export turnover. Frozen fillets accounted for 78% with the remainder consisting of whole frozen tilapia and frozen cuts.
(seafood.vasep.com.vn) After a volatile first half of the year, Vietnam’s pangasius exports to Brazil registered robust growth in July and August 2026. In August alone, export turnover reached $19 million, surging 73% compared to the same period in 2025. Cumulatively for the first eight months, total export value reached $124 million, reflecting an 8% year-over-year increase.
(seafood.vasep.com.vn) Besides modifying their boats, many fishermen in Dak Lak province are making efforts to venture out to sea to harvest seafood during the rough sea season.
(seafood.vasep.com.vn) At the Responsible Seafood Summit and TCRS Shrimp Summit 2026, organized by the GSA (Global Seafood Alliance) in Bangkok, Thailand, the conversation about the future of the shrimp industry began with one of its most important foundations: seedstock quality.
(seafood.vasep.com.vn) In the first eight months of 2026, Vietnam’s tuna exports to Lithuania surpassed $14 million, up 8% year on year. While the increase remains modest, it is notable given the continued pressure on Vietnamese tuna exports to the EU as a whole. More importantly, export turnover to Lithuania has shown a clearer recovery in recent months, making the market a destination worth monitoring for Vietnamese businesses in Europe.
(seafood.vasep.com.vn) Vietnam’s squid and octopus exports exceeded $527 million in the first eight months of 2026, marking a 15% year-on-year increase. This growth is particularly notable given the strong baseline established in 2025, when export turnover for the same period reached $458 million, a 13% rise from 2024.
VASEP - HIỆP HỘI CHẾ BIẾN VÀ XUẤT KHẨU THỦY SẢN VIỆT NAM
Chịu trách nhiệm: Ông Nguyễn Hoài Nam - Phó Tổng thư ký Hiệp hội
Đơn vị vận hành trang tin điện tử: Trung tâm VASEP.PRO
Trưởng Ban Biên tập: Bà Phùng Thị Kim Thu
Giấy phép hoạt động Trang thông tin điện tử tổng hợp số 138/GP-TTĐT, ngày 01/10/2013 của Bộ Thông tin và Truyền thông
Tel: (+84 24) 3.7715055 – (ext.203); email: kimthu@vasep.com.vn
Trụ sở: Số 7 đường Nguyễn Quý Cảnh, Phường An Phú, Quận 2, Tp.Hồ Chí Minh
Tel: (+84) 28.628.10430 - Fax: (+84) 28.628.10437 - Email: vasephcm@vasep.com.vn
VPĐD: số 10, Nguyễn Công Hoan, Ngọc Khánh, Ba Đình, Hà Nội
Tel: (+84 24) 3.7715055 - Fax: (+84 24) 37715084 - Email: vasephn@vasep.com.vn