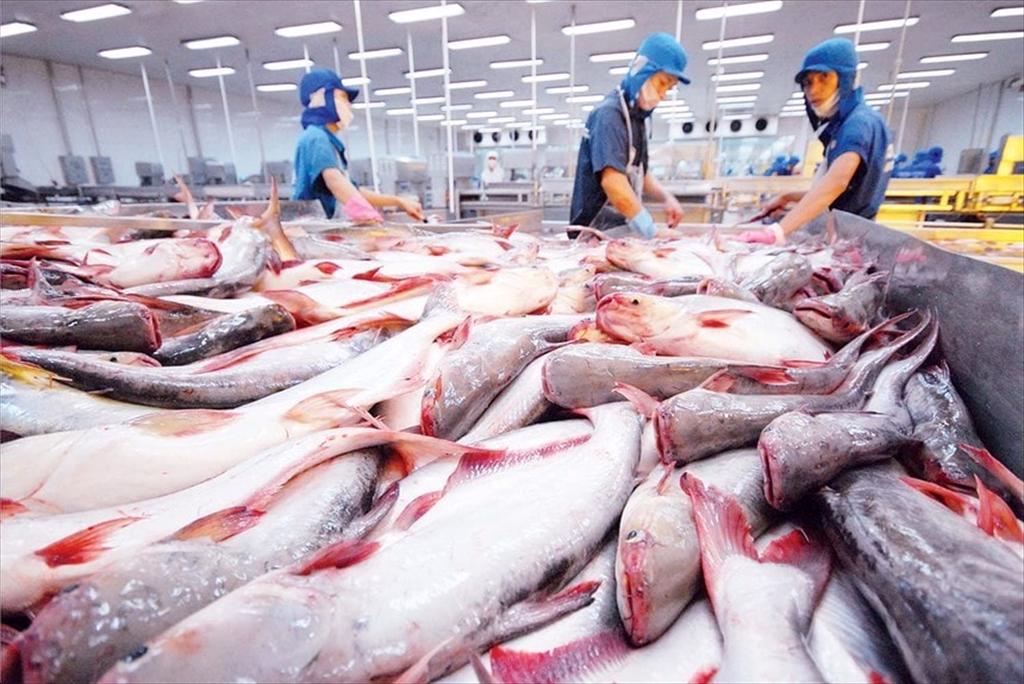
However, for this recovery to translate into sustainable growth, the pangasius industry must continue strengthening key foundations throughout the value chain—from seed quality and raw material supply stability to environmental risk management, processing efficiency, and by-product utilization. These are not only immediate requirements but also essential conditions for enhancing the competitiveness of Vietnamese pangasius as global markets increasingly demand higher standards of quality, traceability, and value addition.
Seed Quality: A Foundation That Needs Continued Improvement
Seed quality remains one of the most critical factors directly affecting farming performance and the competitiveness of the entire pangasius value chain.
While seed supply is relatively abundant in terms of quantity, quality remains inconsistent among hatcheries and breeding facilities. The survival rate from fry to fingerlings is still modest, and losses during the nursery stage continue to be a challenge that requires further improvement.
Improving seed quality should therefore remain a long-term priority for the industry. Healthy, uniform, and well-managed fingerlings can help farmers reduce disease risks, improve survival rates, increase productivity, and contribute to a more stable raw material supply for processing and export enterprises.
Raw Material Supply: Enhancing Stability for Long-Term Production Planning
For processors and exporters, fluctuations in raw material supply can affect production schedules, delivery commitments, and the ability to fulfill long-term contracts.
Strengthening linkages among processors, farming areas, hatcheries, and farmers remains a key solution for reducing volatility, sharing risks, and creating a more stable foundation for the entire pangasius value chain.
Deep Processing and By-products: Significant Potential for Value Creation
Beyond farming, processing and by-product utilization offer substantial opportunities to enhance the value of the pangasius industry.
Producing 1 kilogram of finished pangasius fillet typically requires about 2.8 kilograms of whole fish. The remaining portions—including heads, bones, skin, fat, trimmings, and other by-products—can become valuable raw materials for industries such as food processing, animal feed, pharmaceuticals, cosmetics, and other value-added products if utilized effectively.
In fact, several leading pangasius companies have already invested in deep processing and by-product utilization to produce fish oil, fishmeal, collagen, gelatin, and other higher-value products. This approach aligns with circular economy principles, helping businesses reduce waste, improve resource efficiency, and enhance profit margins.
However, at the industry level, by-product utilization remains uneven. A considerable portion of by-products is still not being fully exploited. With better organization and investment, this segment could become an important pillar helping Vietnamese pangasius shift from a volume-driven advantage to a value-driven advantage.
Climate Change and Disease Risks: Challenges Requiring Proactive Management
The pangasius industry in the Mekong Delta is increasingly affected by climate variability, salinity intrusion, water quality changes, and disease risks.
Due to its intensive farming characteristics, pangasius is particularly sensitive to fluctuations in temperature, water quality, and pond environmental conditions.
In this context, the industry's priority is not merely to expand production but also to strengthen farming area management, environmental monitoring, disease control, and the adoption of safer and more resource-efficient farming practices.
Proactive adaptation to climate-related challenges will help farmers reduce risks while enabling processors to maintain a stable supply and better meet sustainability requirements from importing markets.
Strengthening the Entire Value Chain to Enhance Competitiveness
The export recovery seen in the first months of 2026 is a positive signal for Vietnam’s pangasius sector. However, for growth to be driven by more than just production volume and raw material prices, the entire value chain must continue evolving toward greater stability, efficiency, and value addition.
This requires close coordination among hatcheries, farmers, processors, local authorities, and government agencies. Key priorities include improving seed quality, developing integrated farming areas, stabilizing raw material supplies, expanding deep processing, maximizing by-product utilization, and adopting circular economy models.
With a stronger and better-organized value chain, Vietnamese pangasius will be better positioned to enhance its competitiveness, maintain market share in traditional destinations, and expand into higher-value market segments worldwide.
(seafood.vasep.com.vn) Although Germany’s tuna imports have declined, Vietnam’s tuna exports to the market continue to show positive signs. Notably, export value recovered strongly in Q3/2026, and German import data also show Vietnamese products strengthening their position amid competition among suppliers.
(seafood.vasep.com.vn) Seafood exports are holding double-digit growth, but the opportunities are not spread evenly across product groups and markets. As businesses draw up their plans for 2027, Vietnam Seafood Summit 2026 (VSS2026) offers a chance to look ahead together: what to sell, where to sell it, and how to prepare for growth in the coming years.
(seafood.vasep.com.vn) With less than two weeks to go, the Vietnam Seafood Summit 2026 (VSS 2026) will officially take place in Can Tho. Under the theme “Seafood Market Outlook 2027–2029 – Opportunities and Potential for Double-Digit Export Growth,” the Summit is organized by VASEP at a time when seafood businesses are facing rapid market shifts, changing buyer demand, trade policy changes and growing competitive pressure all at once.
(seafood.vasep.com.vn) On October 28, 2026, the China Fisheries & Seafood Expo opened in Qingdao, China. The expo takes place over three days from October 28 to 30, 2026. This is a prestigious specialized seafood exhibition organized annually by Sea Fare Exposition Inc.
(vasep.com.vn) In the first nine months of 2026, Vietnam’s tilapia exports to the CPTPP bloc reached $7 million, marking a 51% year-on-year increase. The bloc rstands as the fourth-largest market for Vietnamese tilapia, trailing Brazil, the US, and Saudi Arabia.
(vasep.com.vn) VASEP has officially announced the program for Vietnam Seafood Summit 2026 (VSS 2026), featuring five in-depth sessions covering industry outlooks, trade barriers, buyer demand, the domestic market, and solutions to improve productivity and reduce costs across the seafood value chain.
(vasep.com.vn) Vietnam’s shrimp exports reached US$3.7 billion in the first nine months of 2026, up 11% year on year. Although growth has been supported by China and several markets within the CPTPP, momentum is slowing as exports to the United States and the European Union decline. Tariff pressures, international competition, and raw material challenges are creating significant hurdles for exporters in the final months of the year.
(vasep.com.vn) Markets are changing faster, buyer requirements are becoming more demanding, and trade barriers are growing increasingly complex. In this environment, seafood businesses need more than an understanding of current market conditions. They need a longer-term perspective to answer a critical question: Where will growth opportunities come from in 2027–2029, and what should businesses do now to prepare? This is one of the key reasons why VASEP is organizing Vietnam Seafood Summit 2026.
(vasep.com.vn) In the first eight months of 2026, Vietnam’s pangasius exports to the Middle East reached US$113 million, up 7% year on year from the same period in 2025. Growth has become more pronounced in recent months. In August alone, exports to the region totaled US$20 million, an increase of 24%. This indicates that demand for Vietnamese pangasius in the Middle East is gradually recovering after a slowdown in March, although the pace of recovery varies across markets.
(vasep.com.vn) China’s shrimp imports continued to grow strongly in 2026, while Vietnam’s shrimp exports to the market also recorded notable growth. However, behind these positive figures lie two distinct trends: Chinese consumption is growing more slowly than imports, and lobster accounts for a substantial share of Vietnam’s shrimp exports to China, making its product mix significantly different from those of Ecuador and India. Exporters therefore need to assess each segment carefully to understand the opportunities and risks.
VASEP - HIỆP HỘI CHẾ BIẾN VÀ XUẤT KHẨU THỦY SẢN VIỆT NAM
Chịu trách nhiệm: Ông Nguyễn Hoài Nam - Phó Tổng thư ký Hiệp hội
Đơn vị vận hành trang tin điện tử: Trung tâm VASEP.PRO
Trưởng Ban Biên tập: Bà Phùng Thị Kim Thu
Giấy phép hoạt động Trang thông tin điện tử tổng hợp số 138/GP-TTĐT, ngày 01/10/2013 của Bộ Thông tin và Truyền thông
Tel: (+84 24) 3.7715055 – (ext.203); email: kimthu@vasep.com.vn
Trụ sở: Số 7 đường Nguyễn Quý Cảnh, Phường An Phú, Quận 2, Tp.Hồ Chí Minh
Tel: (+84) 28.628.10430 - Fax: (+84) 28.628.10437 - Email: vasephcm@vasep.com.vn
VPĐD: số 10, Nguyễn Công Hoan, Ngọc Khánh, Ba Đình, Hà Nội
Tel: (+84 24) 3.7715055 - Fax: (+84 24) 37715084 - Email: vasephn@vasep.com.vn